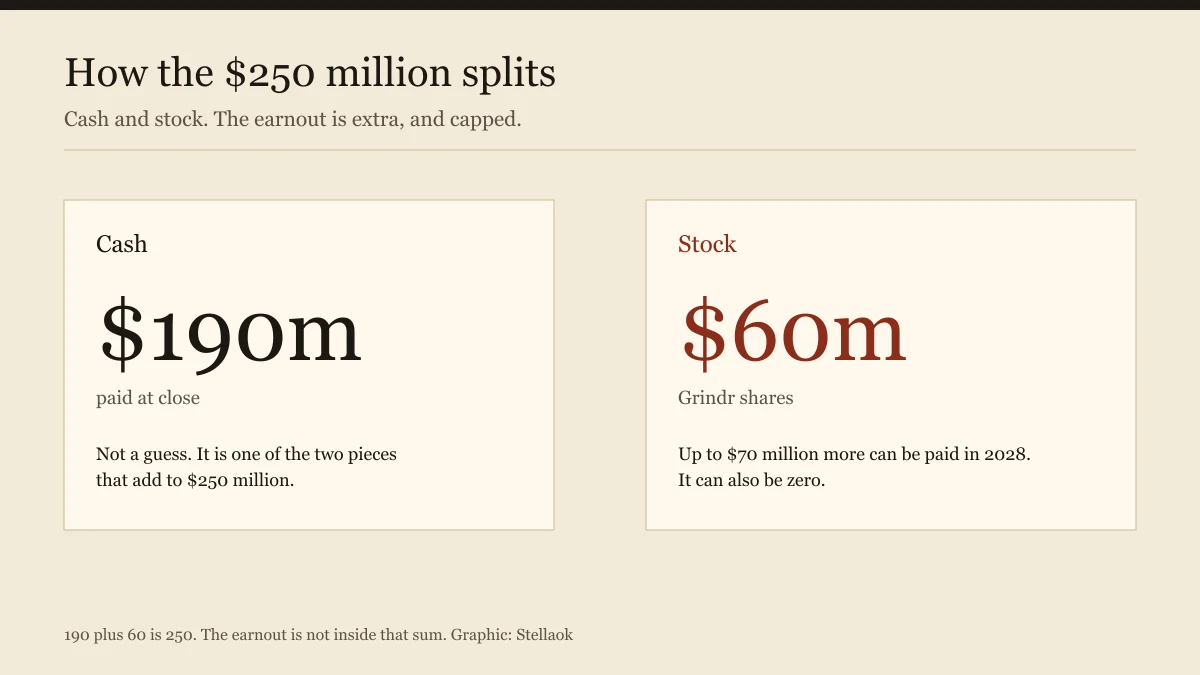
Grindr is paying $190 million in cash and $60 million in stock for PurposeMed. Add them and you get the $250 million in the headline. There is no third piece inside that $250 million.
CNBC also describes an earnout of up to $70 million in cash, tied to Freddie's results in 2027 and payable in 2028. "Up to" caps that cheque. It does not promise the cheque. One hundred and ninety plus sixty plus seventy is $320 million only if the earnout pays in full. The agreed price, before any earnout, is $250 million.
$4,800 a year is twelve times a floor
This is Grindr's first major acquisition since it was founded in 2009. The point is to grow Woodwork, the healthcare offer it launched in 2025, next to subscriptions and advertising. Chief executive Arison said the business needs pharmacies and clinicians, and that more patients improve utilization until "you're in a very high margin profile."
The company expects the combined US telehealth and pharmacy operation to produce more than $400 a month per active patient. Twelve times $400 is $4,800, so a patient who stays a full year is worth more than $4,800 on that wording. The "more than" makes $4,800 a floor, not an average invoice. At 50,000 US patients, Arison's estimate is roughly $240 million a year. Fifty thousand times $4,800 is exactly $240 million, so that revenue sketch uses the floor rate and a round patient count. It is not revenue the company has reported. Freddie has served more than 55,000 US patients. That is another floor, and it counts people served, not the 50,000 actives in the sketch.
Freddie started in Canada in 2020, crossed into the United States in 2024, and now covers all 50 states and Washington, D.C. PrEP, taken as prescribed, can cut the risk of getting HIV from sex by 99 percent. Arison hopes to take annual PrEP growth of 10 percent and "maybe double that." On his arithmetic, that would mean about 300,000 more people on PrEP over five years and roughly 5,000 people who do not get HIV. Both of those are conditional on the doubling. They are not a result.
The capital number waits until November
Grindr says the deal should add to EBITDA dollars immediately, and that building the US operation still requires investment. Arison will tell shareholders in November how much. He expects those margins to approach the core business, which he put at more than 40 percent. "More than 40 percent" is a floor, and "eventually" is not a fiscal quarter.
A firm covering the shares moved them to overweight and lifted a price target from $16 to $18. A fee on a card network is a different kind of toll. Apple's ask in India is 0.2 percent, cut out of a thinner payments margin. Households are already losing ground where 3.4 percent inflation outruns 3.1 percent wage growth.
"We're doing exactly what we promised the street," Arison said. The street still does not have the November investment figure. What can be added on the day of the announcement is the headline: $190 million cash, $60 million stock, and an earnout that can be zero.
The app, CNBC notes, is used by millions of people globally. Grindr estimates about 400,000 US users currently indicate on their profiles that they take PrEP, and that more than two million additional US users could benefit from the medication. The 400,000 is a profile field. The "more than two million" is a could-benefit estimate. Neither is the 50,000 active patients in the $240 million sketch, and neither is the more than 55,000 patients Freddie has already served. A price target moving from $16 to $18 is one firm's model. It is not evidence that sketch has become revenue. November is the date Arison set for the capital figure that is still missing.